


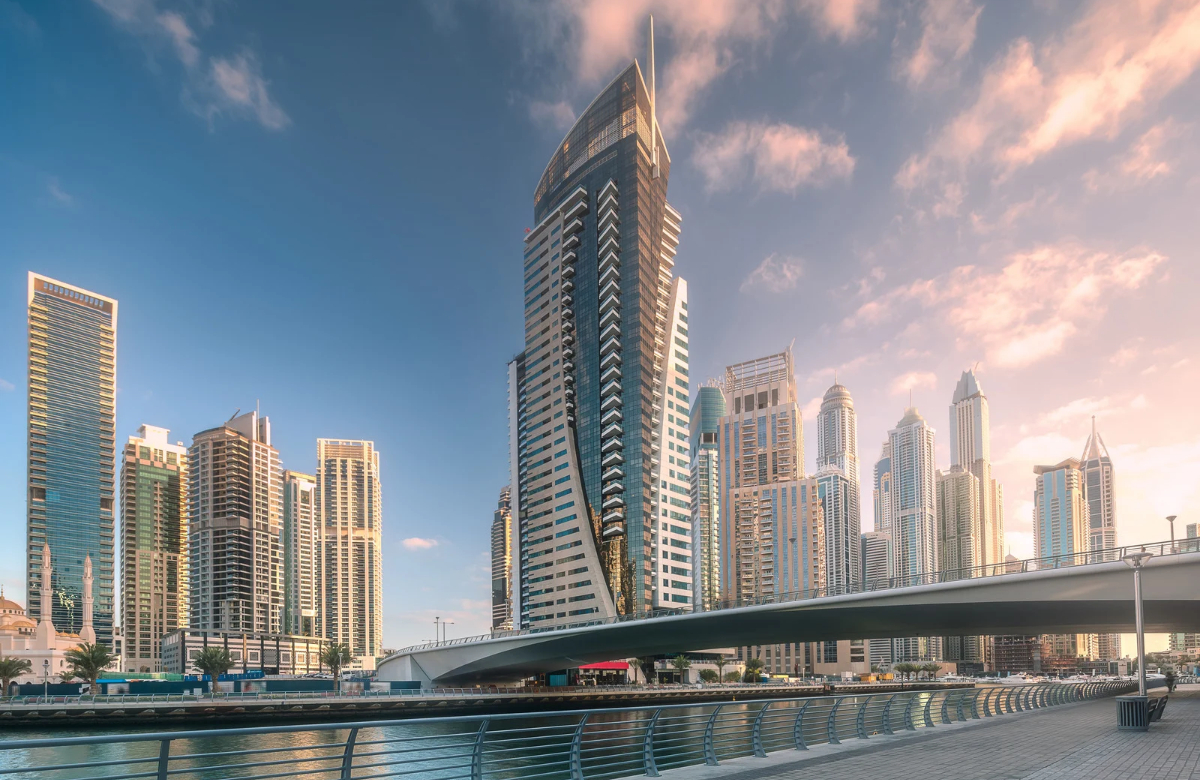
Furnished short-term rental apartments in Dubai are no longer targeting only people visiting the city. Following the geopolitical turmoil that hit tourism in spring 2026, part of the market shifted towards people who already live there and need temporary accommodation.
The change was not limited to discounts. It included monthly pricing, longer stays and listings on residential property platforms, beyond the usual tourist booking channels.
The alternative market was already there
According to an AirDNA analysis published on September 30, stays of at least 28 nights accounted for 45.5% of market revenue in April, compared with 17.4% a year earlier.
This was not an entirely new model. Longer stays were already an important part of the market, particularly during the summer, when the heat limits tourist activity. The crisis accelerated the shift towards this customer segment.
In April, the number of properties securing a short-term booking fell by 38.8% year over year. By contrast, those receiving a mid-term stay booking increased by 38%. These changes refer to the number of properties with a booking, not the number of bookings or nights.
From Airbnb to residential property platforms
GuestReady describes how this adjustment was implemented across its own portfolio, which includes more than 400 homes in Dubai.
In addition to Airbnb and Booking.com, it listed properties through Property Finder, Bayut and Blueground, targeting people looking for furnished accommodation with monthly pricing.
These customers are not comparing the cost of a weekend stay, but their total housing costs. They include residents who are relocating or prefer a temporary solution rather than signing a new annual lease.
From April to early August, around 45% of the company’s bookings came from people who were already in the UAE. The figures relate exclusively to GuestReady and do not represent a measurement of the entire market.
Higher occupancy, but not necessarily higher revenue
The shift limited the losses, but did not eliminate them. AirDNA estimates that total market revenue in April fell by 51.8% year over year, as rates declined across both stay categories.
The same gap between occupancy and revenue appears later in the year. In September, GuestReady recorded occupancy of 88.4%, compared with 82.5% last year. However, the average daily rate was 9% lower, while revenue per available night remained down 3%.
The figures highlight a different dimension of the recovery. A full calendar does not prove that the same guests have returned at the same rates. It may mean that the property is now serving a different need.
For the Dubai market, the next question is whether the return of tourists will restore returns or whether the combination of tourist stays and temporary housing will take on a more permanent role.
