


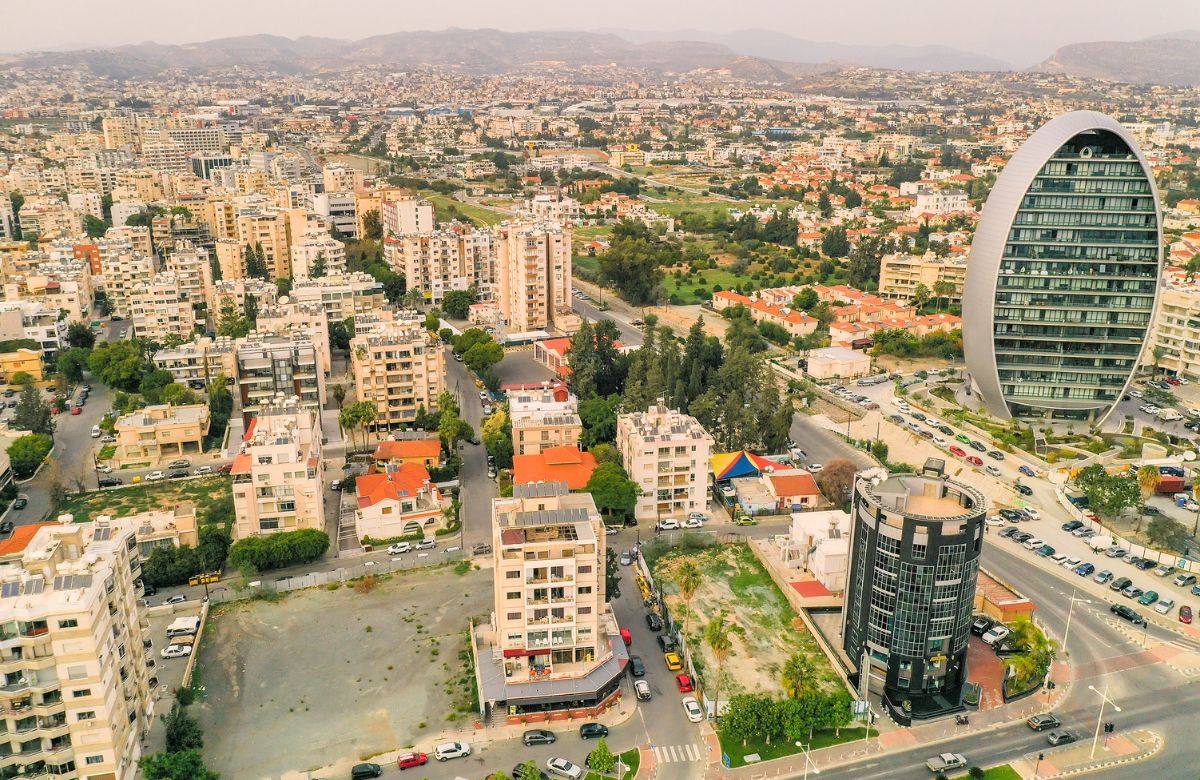
The real estate market in Cyprus is at a peculiar turning point, where demand remains active but actual transaction activity is noticeably constrained. The issue is not a lack of interest, but rather limited access to financing, which is acting as a key “brake” for a significant share of potential buyers.
Recent data from the Central Bank of Cyprus confirm that demand for housing loans strengthened towards the end of 2025. However, banking criteria remain strict, limiting actual loan disbursements and, consequently, the completion of property transactions.
Strong demand momentum, driven by foreign buyers
Despite financing constraints, demand in the Cypriot property market remains strong and multi-layered. It is driven not only by domestic households but also by international investors, who are playing an increasingly important role.
It is indicative that around 40% of transactions in 2025 involved foreign buyers, while in areas such as Paphos and Larnaca, purchases by overseas investors even exceed domestic demand. At the same time, more than 1,600 property acquisitions by foreign investors were recorded within a single year, with strong participation from Europe, Israel, and Russia. This international demand acts as a “buffer” for the market, supporting prices and absorbing a significant share of available supply.
Steady price growth for Cyprus real estate market
The Cypriot property market continues to record an upward trajectory in prices, albeit at a more moderate pace compared to previous years. In 2026, property prices are increasing by an average of 5% to 8%, confirming the market’s stability.
Prices remain high, with an average apartment costing around €458,000 and houses reaching up to €850,000, depending on location and characteristics.
At the same time, the market maintains a strong investment profile, with rental yields ranging between 4% and 6%, further boosting interest for both owner-occupation and investment purposes.
Rising supply, but transactions remain constrained
Construction activity is also strengthening significantly. Building permits increased by approximately 36%, indicating that the market is preparing for further supply expansion in the coming years.
However, this increase in supply does not automatically translate into higher transaction volumes. Although property sales rose by around 11% in early 2026, this growth does not fully reflect underlying demand, as a large portion of interested buyers are unable to complete purchases due to financing restrictions.
A two-speed market
The result is the formation of a “two-speed” market. On one hand, modern, energy-efficient, and properly priced properties—mainly newly built homes—continue to be absorbed. On the other hand, older or less competitive properties remain on the market for longer periods.
This divergence is further reinforced by the fact that banks tend to favor “safer” properties and borrowers, leading to unequal access to financing and, ultimately, uneven transaction speed.
The key issue is not price, but purchasing power
The Cypriot real estate market is no longer operating in a traditional price cycle, but rather in a liquidity cycle. The critical question is no longer how much a property costs, but who can actually afford to buy it.
Buyers with sufficient equity or strong credit profiles are moving more flexibly, while those relying on bank financing face significant barriers. This is leading to deeper segmentation in the market, which is expected to intensify.
Geopolitical factors and external pressures
The international environment adds another layer of complexity. Developments in the Middle East and the war in Ukraine are affecting the market in two ways. On one hand, they are boosting demand from foreign investors seeking safe havens, particularly in newly built and tourism-related properties. On the other hand, geopolitical uncertainty keeps global borrowing costs high, impacting interest rates and further restricting access to financing.
Outlook: Stable market, but limited mobility
The overall outlook for 2026 points to a resilient market, with strong demand and stable prices, but clear limitations in liquidity. If lending conditions do not ease, the market is expected to operate with lower transaction volumes, stronger competition among sellers, and even greater segmentation between buyer groups.
