


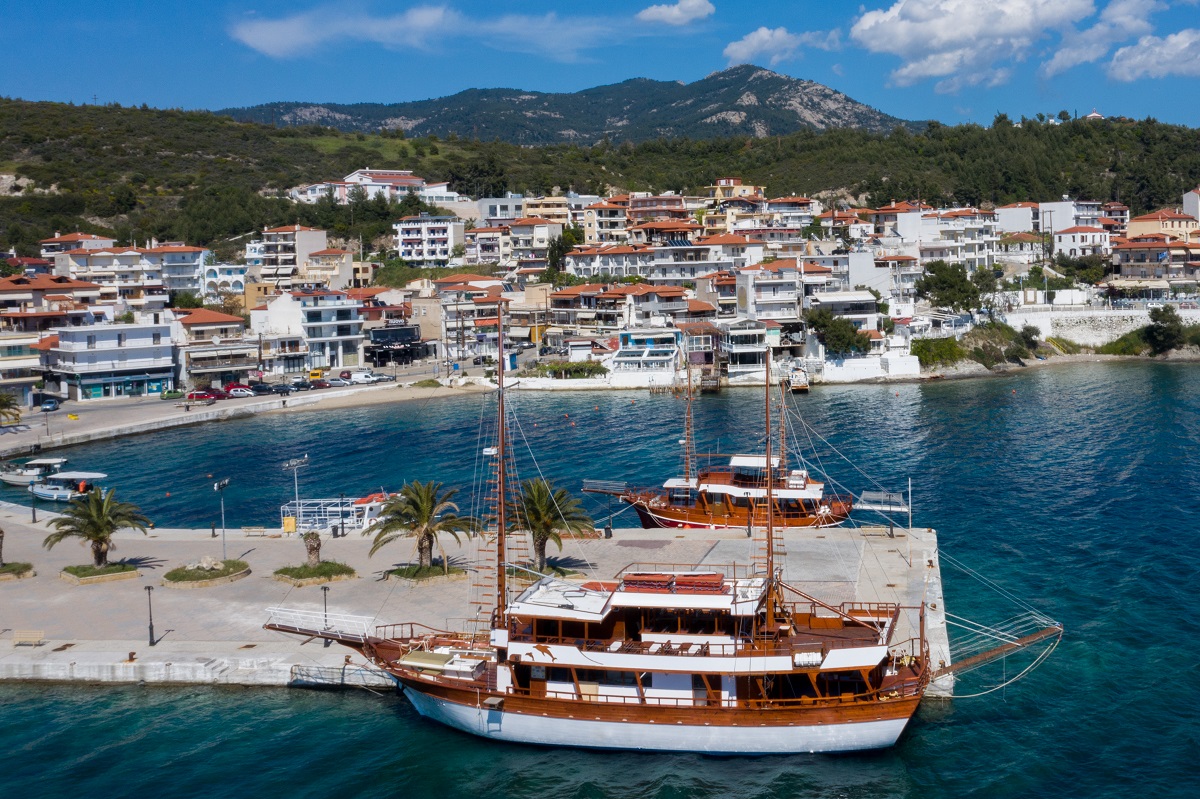
With nightly rates exceeding €300 in popular holiday destinations and reaching €363 in the villa category, Halkidiki maintained its position among the most expensive short-term rental markets in Northern Greece this summer. The difference compared with Thessaloniki is particularly significant, as the average indicative nightly rate in Halkidiki reached €154 in August, compared with €57 in Thessaloniki. This represents a cost approximately 2.7 times higher, while in areas such as Sani, where rates reached €302, the difference exceeded fivefold.
Behind these figures are two markets with different characteristics, both in terms of accommodation types and the length of the tourist season. Halkidiki relies primarily on summer holiday demand, with larger homes, family accommodation and luxury villas, while Thessaloniki maintains more consistent activity throughout the year, supported by urban tourism, business travel and major trade fairs and cultural events.
This picture is outlined to BnBNews.gr by Dimitris Missas, Corporate Investments and Hospitality Business Development Consultant and member of the Board of Directors of the Short-Term Accommodation Managers Association (STAMA), who presents data on market performance during 2026. As he explains, the substantial differences in rates are not solely due to stronger tourist demand in Halkidiki during the summer months, but also to the different composition of the accommodation supply.
In Thessaloniki, a significant proportion of accommodation consists of small apartments suitable for couples or individual travellers. By contrast, a large part of the Halkidiki market consists of larger holiday homes capable of accommodating families or groups of six to eight people. Therefore, the higher nightly rate does not necessarily translate into a correspondingly higher cost per guest.
How nightly rates changed in Halkidiki
The data presented by Mr Missas highlight the strong seasonality of Halkidiki’s short-term rental market, with rates gradually increasing from June, peaking in August and declining noticeably in September.
More specifically, the average indicative nightly rate across all accommodation types stood at €130 in June, increased to €148 in July and reached €154 in August. Over two months, an increase of approximately 18.5% was recorded, reflecting stronger holiday demand as the summer peak approached.
The picture changed in September, when the average rate fell to €118, marking a decline of approximately 23% compared with August. This development highlights the market’s heavy dependence on the summer season, as the end of the holiday period and the gradual departure of visitors lead to lower rates.
Even greater differences emerge between individual property categories. For apartments, the average indicative rate started at €101 in June, increased to €119 in July and reached €126 in August, before falling to €92 in September.
In the villa category, however, rates were considerably higher. In July, the average indicative nightly rate stood at €344, while in August it increased to €363. Even in September, when tourist demand had begun to decline, rates remained at €261.
This difference reflects the particular strength of the market for larger and luxury holiday homes. These properties cater to a different audience, have more bedrooms and often offer upgraded amenities, allowing owners to set significantly higher rates during the peak season.
Average indicative nightly rates in Halkidiki
Accommodation Type | June | July | August | September |
|---|---|---|---|---|
| All accommodation | €130 | €148 | €154 | €118 |
| Apartments | €101 | €119 | €126 | €92 |
| Villas | — | €344 | €363 | €261 |
Significant differences are also recorded between individual areas of Halkidiki, with Sani and Nikiti standing out for their high accommodation costs. In Sani, the average indicative nightly rate reached €271 in July and increased to €302 in August, recording a rise of approximately 11.4% in just one month. This level was almost twice the average rate in Halkidiki during the same month, confirming the considerable differences found in areas with a high concentration of quality holiday homes.
Similarly, in Nikiti in Sithonia, indicative rates for houses ranged between €211 and €226 during the two peak summer months. These figures show that even within the same regional market, significant differences exist, linked to the location, size and characteristics of the properties on offer.
The comparison with Thessaloniki is particularly revealing. In August, when the average indicative nightly rate in the city stood at €57, it exceeded €300 in Sani. This means that the cost per property in this particular holiday destination was approximately 5.3 times higher.
The difference narrowed in September, although it did not disappear. The average rate in Thessaloniki stood at around €62, compared with €118 in Halkidiki, with the latter remaining almost twice as expensive even after the peak summer season.
Mr Missas points out, however, that these comparisons require caution. A small apartment in central Thessaloniki is not the same tourism product as a seaside house or a villa capable of accommodating more people. Consequently, the differences in rates reflect both seasonality and the different composition of the two markets.
Summer demand trends and occupancy rates
Despite the high rates recorded during the peak months, this year’s tourist season in Halkidiki did not begin with the same momentum seen in 2025. According to Mr Missas, available reports from the hotel market indicated weaker demand during the early summer months compared with the particularly strong previous year. However, the situation improved significantly in August, when hotel occupancy rates reached levels between 90% and 100%.
These percentages refer to the hotel market rather than short-term rental accommodation. Nevertheless, they provide an indication of overall tourism activity in Halkidiki, where August continues to account for the largest share of demand.
Strong seasonality is one of the main challenges facing property owners and managers. Although high rates during July and August can boost revenue, a property’s overall financial performance depends on the actual number of bookings, the length of its operating season and management expenses. Particularly for larger homes and villas, maintenance, cleaning and operating costs are higher. Consequently, a high nightly rate does not automatically translate into correspondingly high net profitability.
